Perhaps one cannot find a better example of disruption in business models, especially in marketing models, than the impact of the internet and of the consequent digitalization of business, especially the service-based businesses over the last two decades. Not surprisingly, many cases submitted for this textbook were based around digital innovation (Chapter 7). Bank Alfalah is one such example that set its goal as providing ‘convenience to its customers’ and offered new services by building ‘digital leadership’ and embedding it into its vision and strategy. It introduced Pakistan’s first digital account opening product and banking solution RAPID, and its Alfa App was revolutionary in the Pakistani market. Bank Alfalah also led the SBP’s Roshan Digital Account initiative (Dr. Aamir Khan, Case Advisor).
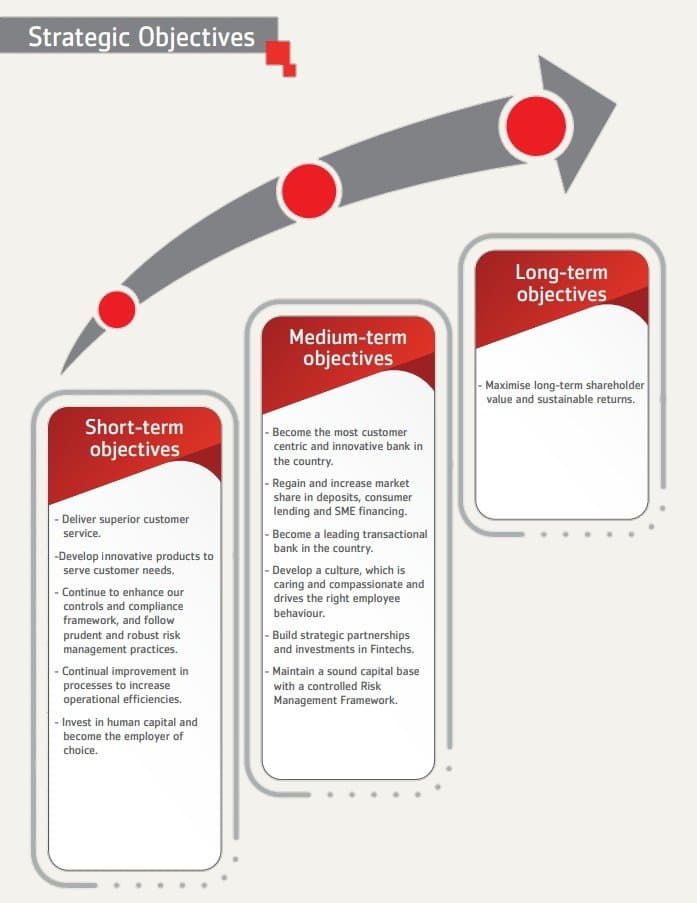
The case chronicles the growth of Bank Alfalah in Pakistan, ushering in a digital era. Led by its President; it has rebranded itself as the pioneer in digital advances. Staying true to its mission statement which states “We look at the market with fresh eyes to find new opportunities, seek new ways of enabling our customers to succeed and advance the world of finance”, Bank Alfalah has consistently introduced path-breaking innovations to the banking industry.
Introduction
Bank Alfalah was incorporated almost 25 years ago on June 21, 1997, as a public limited company. When it first commenced its operations, it had only three branches and offered limited services. Today Bank Alfalah is the seventh largest Bank in Pakistan with a network of over 900 branches in more than 200 cities across Pakistan. It has an international presence in Bangladesh, Bahrain, Afghanistan, and a representative office in the UAE. The major shares of the Bank are owned by the royal group of UAE.
Bank Alfalah’s performance in 2021 reflects another year of sound financial result amidst the global COVID-19 pandemic. The bank posted impressive financial results for the year ended 31 December 2021, with the Bank registering a profit before taxation of PKR 23.37 billion. The Bank’s Profit after tax was recorded at PKR14.22 billion in December 2021 as compared to Rs.10.48 billion in December 2020.
Bank Alfalah has the widest range of financial products and services. For its customer-centric approach towards financial services, the Bank has received the Best Digital Banking,
and the Best Housing Finance Award by Pakistan Banking Awards in 2022.
In addition to the efforts towards building a large product suite, the Bank also believes in giving back to society. Bank Alfalah has continuously striven to offer new services and increase convenience to its customers, as well as protect the welfare of society. The Bank considers corporate social responsibility, under the identity of Rah-e-Falah, as one of the most important aspects of its business. As part of the CSR initiatives, the bank has partnered with multiple NGOs that are working for social welfare and in the education, healthcare sectors.
The Head Office of Bank Alfalah is located at I.I Chundigar Road, the hub of the country’s financial industry where the head offices of all major banks are situated.
Bank Alfalah’s Five Years Strategy and Vision
Bank Alfalah’s Chairman, His Highness Sheikh Nahayan bin Mubarak Al Nahayan, has been influential in setting Bank Alfalah on the path to having a sizeable footprint serving millions of consumers, corporations, institutions, and federal and provincial governments. The growth of Bank Alfalah has been guided by its top management’s continued commitment to providing creative, convenient financial solutions. His Highness Sheikh Nahayan bin Mubarak Al Nahayan, believes that if the customers are provided with convenient financial solutions, the Bank will be rewarded with success in Pakistan and beyond.
Taking a cue from Bank Alfalah’s Chairman, His Highness, the bank’s President, and CEO, Mr. Atif Bajwa, set Bank Alfalah on a new path. The year 2015 marked a fresh new beginning for the bank. Their vision was to become a financial institution known for being innovative and inspiring. Even though Bank Alfalah had consolidated its position as one of the top banks in the country, the management was very mindful of the competition at its heels. The market share declined as new banks entered the market. In 2015, he was aware that if Bank Alfalah was to remain a leading player in the market, it must have a distinctive competency. While Bank Alfalah could focus on a customer-centric attitude, strong culture, and mutually beneficial alliances with subsidiaries, what could set it apart from other banks could be its focus on innovation. Not only would Bank Alfalah’s commitment to innovation be a source of competitive advantage, but it would also be difficult to imitate and replicate if Bank Alfalah was steadfast in executing its strategy of being the market leader in introducing cutting-edge technology to the industry.
The President decided to leverage digital technology to make headway on two fronts: as an infrastructural platform for growth that brings the unbanked into the fold of banking as well as cater to the needs of existing banking customers who wanted digital solutions at their fingertips and were becoming increasingly tech-savvy. Driven by the vision of its President, Bank Alfalah committed itself to innovation and digitization.
Staying the Course: Bank Alfalah’s Continued Commitment to Innovation
Post Covid-19 pandemic, the need for a digitized world not only accelerated the need for digital offerings for consumers and merchants, but it also became a necessary tool for business survival.
Limited branches were open during the lockdown period and the requirement to convert consumers from bricks to clicks was ever more necessary. Furthermore, with internet users increasing by 11 million (FY 2019-2020) in Pakistan and the eCommerce sector booming with revenues increasing by PKR 7.1 billion in Q4 FY20, to bring annual eCommerce revenue to PKR 34.8 billion, it was clearly visible that the Pakistani market was rapidly transforming digitally, however, the banking sector wasn’t evolving at the same pace. Customers needed an end-to-end digital banking tool that allowed them to conduct banking activities from the comfort and safety of their homes.
Mobile Bank Application – Alfa
In this day and age where customers are bombarded with numerous digital offerings to facilitate them in performing various different transactions for example, bill payment, money transfer, mobile top-up, school fee payment, etc., showcasing Alfa as a lifestyle app, offering solutions for all lifestyle needs, was their unique selling point. With the introduction of the Alfa App, the idea of going to bank branches was checked off because all the services became just a click away.
Alfa is a mobile banking App that offers a one-stop solution for all banking needs. It enables customers to manage their savings, borrow money, track expenses, pay bills and fees, open full-fledged accounts, request for cheque book, or apply for credit cards; all digitally.
Alfa App has transformed itself from a banking to a lifestyle app, offering a one-stop solution for all the banking and lifestyle needs of customers. Alfa App is focused on giving an unmatched experience to the customers with its newly updated UI/UX, which makes it easier for all the customers to navigate through the app.
Alfa App is not just designed for Bank Alfalah customers; it can be accessed by anyone who downloads the app and avails multiple features of the app.
The business performance has been impressive, as can be seen in Exhibit 1:
2016
2017
2018
2019
2020
2021
2022
30 Days Active Users (in thousands)
51.4
85.1
123.8
146.7
216.7
354.7
510.2
Transactions– Core (in Millions)
1.4
2.7
4.4
5.7
8.9
16.1
12.4 36.1
Volume – Core (in Billions)
39.4
88.8
154.2
174.2
294.9
651.7
1,155.6
Exhibit 1: Business Performance of Alfa
*Digital Transaction Ratio= Total Digital Transactions performed in a year /Total Banking transaction excluding trade and treasury transactions.
RAPID
Understanding the needs of the market Bank Alfalah, introduced Pakistan’s first digital banking platform; RAPID.
Alfalah RAPID is an innovative and revolutionary banking solution geared to fulfill all onboarding and self-service needs of our customers. RAPID is an acronym for Responsive, Agile, Powerful, Instant & Digital.
Now customers can open their new accounts, apply for debit and credit cards, avail personal loans, and so much more from the comfort of their homes/offices through a completely digitized and convenient online journey offered via the digital touchpoints in-branch or self-service through Web Portal and Alfa Mobile App.
Key Features of Rapid Account Opening (Impact on customers):
- Paperless, fully digital customer onboarding.
- Open Conventional or Islamic banking accounts from anywhere in Pakistan with minimal documentation and no additional charges; activation within 1 working day.
- Asaan Digital accounts to cater to the unbanked/underbanked target segment.
- No proof of income requirement for Asaan Digital Accounts having account limits on maximum deposit balance. Account opening within 4-5 minutes with minimal steps.
- Accounts available under both Current as well as Savings variants.
- Access to your bank remotely with an end-to-end digitized process.
- Start transacting immediately upon account activation using our Internet Banking or Alfa Mobile App.
- No physical presence required for document verification or any other purpose.
- In-App Biometric Finger Print Verification through NADRA (National Citizen Database).
Around 80% of Bank Alfalah’s account openings are done through the paperless RAPID platform by the year-end of 2022.
Total accounts activated via RAPID (branch and self-remote) by 2022 are 130,000+.
Roshan Digital Account
Roshan Digital Account is a major initiative of the State Bank of Pakistan (SBP), in collaboration with commercial banks operating in Pakistan. Initially, 8 banks collaborated with SBP and Bank Alfalah is amongst the leading banks for this initiative. This initiative provides an innovative banking solution for millions of Non-Resident Pakistanis (NRPs), including Non-Resident Pakistan Origin Card (POC) holders, seeking to undertake banking, payment, and investment activities in Pakistan.
The structure of Roshan Digital Account offers convenience through digitized solutions and amended tax regimes. The profits on investments made through Roshan Digital Account in Naya Pakistan Certificates, the stock market, mutual funds, and real estate are subject to full and final tax with no requirement of filing tax returns. Furthermore, it has been ensured that overseas Pakistanis have full flexibility and freedom to operate their accounts and repatriate profits to their countries of residence at any time without the need for any approvals.
Alfa Term Deposit
Bank Alfalah further introduced multiple methods of savings with just a few clicks of a button to provide the convenience of not visiting a branch and filling out multiple forms. The Alfa Term Deposit gave the power of saving on the palm of the consumers where customers could book their Term Deposits digitally for as low as PKR 500 within 10 seconds. It further allowed the customers early encashment, change of maturity, and digital downloads for their WHT certificates digitally.
With Islamic Banking on the rise, Bank Alfalah has also introduced an end-to-end digital Term Deposit to cater to Islamic Banking customers who want to secure their savings in Shari’ah compliant manner and earn Riba-Free profit.
For the first time, customers having conventional banking accounts can also book Islamic Term Deposits with the launch of this product.
2020
2021
2022
Amount Invested into TDRs (PKR Mn)
10,427
31,386
43,339
Closing Deposit (PKR Mn)
831.5
2,516
6,297
Total Consumers using Alfa Term Deposit
784
2,084
4,764
The Future
Bank Alfalah’s investment in technology has paid off. Customers perceive Bank Alfalah as a progressive Bank. The profitability has increased from PKR 7.52 billion to PKR 14.22 billion from 2015 to 2021.
As digitalization becomes a “buzzword” and is widely adopted by all players in the industry, and as agile FinTechs enter the market, digitalization that is only skin deep may not suffice. The bank that is able to embed itself into the life of its consumer such that its financial services underpin every need of its customer; be it the purchase of a car, a house, or a retirement plan, will be the one to emerge a leader. The tech-savvy customer is no longer amused by transferring money to a mobile wallet as opposed to giving a cheque, cash, or using an app to pay his utility bill as opposed to physically with cash. Digitization has to continually make the customer experience more convenient, secure, and transparent.
With a rise in electronic payment mechanisms, digital currencies, and a generation of new technology-based service providers coming into the market, Bank Alfalah will have to devise strategies to prevent the erosion of its competitive advantage. It is uniquely placed because it has both the legacy of a well-recognized brand name and the digital infrastructure, know-how, and history of customers to develop future products and services. The bank faces the dual challenge of keeping operating costs in check while building capabilities that fuel growth. As Bank Alfalah continues its march forward, what should be the next steps in its digitization strategy?
Questions to stimulate conversation on the case
- What did Bank Alfalah choose as its distinctive competence?
- Can innovation be a source of Sustained Competitive Advantage? Does it meet all four criteria?
- “There are many a slip between the cup and the lip”. A brilliantly conceived strategy can fail at the stage of execution. How has Bank Alfalah executed its strategy of “Customer service through Innovation” over the years?
- What challenges do you foresee? What strengths can Bank Alfalah leverage to maintain and strengthen its position in the banking industry?
Links and media
Website: https://www.bankalfalah.com/
Digitalization is the key theme in Mobilink Microfinance Bank’s case of ‘Finclusion’. Mobilink Microfinance Bank (MMBL) is the largest digital bank in Pakistan. It realized very early that ‘the old days of doing business could no longer be sustained’, and that any reform should be led by ‘digital initiatives at the core.’ Its solution in the shape of DOST (friend) was a premium digital financial services application, available to users in times of pressing need, and eventually made to all its customers. The bank’s other achievement was its contribution towards women empowerment, offering Bint-e-Hawwa (Daughter of Eve) Current Account and Business Loan, launching its flagship Women Inspirational Network (WIN) program devoted to holistic female empowerment through financial services and literacy (Dr. Aamir Khan, Case Advisor).